How African Commodity Traders Reduce Banking Risk Using a Mauritius Trading Entity. A compliance-first structure for international trade flows.
African commodity traders moving value across borders face a persistent operational threat that is not about demand or pricing. It is about banking continuity. Account closures, elevated AML scrutiny, delayed settlements, and reputational de-risking can break an otherwise profitable trade flow.
This briefing explains how a properly structured Mauritius trading entity, operated with real substance and bank-grade documentation, can reduce banking friction by placing trade flows inside a jurisdiction and operating model that international banks more readily support.
The Core Problem Banks Are Reacting To
Global banks and correspondent banks are under sustained pressure to apply risk-based controls to cross-border payments and trade-linked activity.
When a bank cannot clearly explain a client's ownership, control, counterparties, trade rationale, and documentation quality, it often chooses delay, restriction, or termination rather than ongoing exposure.
- Account closures: Risk committees may exit relationships that are costly to monitor or difficult to document.
- Excessive AML scrutiny: Requests expand from basic KYC into repeated enhanced due diligence and transaction-level proof.
- Delayed settlements: Screening, escalation, and correspondent bank checks increase time to clear payments.
- Reputational de-risking: Banks may reduce exposure to higher-risk corridors or sectors, even when activity is legitimate.
Why Mauritius Changes the Risk Equation
A Mauritius entity does not eliminate AML checks. It improves the way a legitimate trading business is presented and supervised, using a framework that aligns with global AML and transparency expectations and a mature professional-services ecosystem for international business.
Banks tend to respond positively when they see a structure that is easier to understand, easier to audit, and easier to defend to regulators and correspondent partners.
What “Compliance-First” Means in Practice
Compliance-first is not a slogan. It is a design approach where the operating model is built around the evidence a bank will demand before approving and sustaining the relationship. The goal is to be continuously bankable, not just approved once.
- Transparent beneficial ownership: Clear UBO disclosure and control mapping, consistent across all counterparties and banks.
- Economic substance: Real decision-making and administration anchored in Mauritius, not paper formality.
- Trade document discipline: End-to-end document pack consistency, including contracts, invoices, shipping, inspection, and payment trail.
- Risk-based controls: Screening, red-flag escalation, and recordkeeping aligned with FATF risk indicators relevant to trade.
- Proactive bank engagement: Pre-onboarding clarity that reduces surprises, escalations, and sudden freezes.
The Mauritius Trading Entity Model
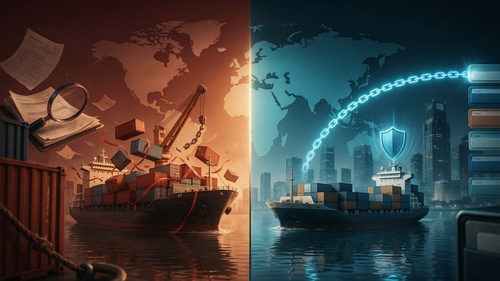
The most bank-supportable use case is when the Mauritius entity is a true commercial counterparty with a clearly documented role. The entity becomes the contracting and settlement hub for international buyers, while sourcing can remain in Africa, supported by verifiable trade documentation.
Typical flow
- Source in Africa: Supplier onboarding, contracts, compliance checks, and commodity provenance documentation.
- Contract through Mauritius: The Mauritius entity acts as principal in the trade contract with the buyer.
- Document the shipment: Shipping, inspection, and title documents match contractual terms and invoice logic.
- Receive buyer funds: Buyer pays the Mauritius entity under the contract with a clean audit trail.
- Pay suppliers and logistics: Outbound payments follow documented obligations with consistent narratives and attachments.
Where Banking Risk Reduces
The risk reduction does not come from secrecy. It comes from reduced ambiguity. Banks are more comfortable when they can defend a client file that is structured, supervised, and evidentially complete.
- Fewer false red flags: Payments align to contracts and shipping evidence, reducing narrative gaps.
- Cleaner correspondent pathway: Better documentation reduces escalations at intermediary stages.
- Lower operational friction: Standardized packs reduce repeated information requests and delays.
- Improved continuity: A stable compliance posture reduces the probability of sudden exits.
Non-Negotiables for Bankability
The fastest way to trigger de-risking is to treat the structure as a shortcut. The bankable approach is conservative and evidence-led.
- No hidden ownership: If ownership or control is unclear, approvals fail or relationships end.
- No weak trade rationale: If the bank cannot understand why Mauritius sits in the middle, scrutiny increases.
- No document inconsistency: Mismatched invoices, dates, weights, or counterparties create repeated holds.
- No substance theater: Substance must be real enough to withstand professional and regulatory review.
Risk Control Blueprint for Commodity Traders
1) Counterparty Risk Controls
- Formal supplier onboarding, including identity, ownership, sanctions screening, and adverse media checks.
- Commodity provenance evidence and third-party inspection where relevant.
- Escalation triggers for unusual routing, price anomalies, or round-amount payments where atypical for the trade.
2) Transaction and Documentation Controls
- One master document checklist used for every shipment and every settlement.
- Clear contract to invoice to shipment mapping, including Incoterms consistency.
- Payment narratives standardized and tied to contract references and shipment identifiers.
3) Governance and Substance Controls
- Board and management decision-making evidenced in Mauritius for core commercial activity.
- Auditable accounting, recordkeeping, and retention processes.
- Use of regulated service providers where required by the licensing and regulatory perimeter.
Commercial Outcomes to Target
- Lower settlement volatility: Fewer surprise holds and fewer repeated clarifications.
- Reduced relationship fragility: Lower probability of sudden account closure when scrutiny rises.
- Higher buyer confidence: International counterparties often prefer paying an entity in a jurisdiction they can diligence easily.
Implementation Path
- Pre-structure risk review: Map current banking failures to root causes in documentation and control gaps.
- Define the Mauritius role: Make the commercial reason explicit and documentable.
- Build the evidence pack: Create standardized onboarding, shipment, and settlement documentation.
- Align governance and substance: Put real decision-making and admin processes in place.
- Bank onboarding strategy: Present a complete story, supported by documents, before the first high-value settlements.
Key Takeaway
Banking risk in African commodity trading increasingly comes down to defensibility. A Mauritius trading entity, used correctly, is a defensible operating structure that improves clarity, supervision, and documentation quality. The win is not avoiding scrutiny. The win is meeting scrutiny with a clean, consistent, auditable story.
Scott Oliver is a retired British writer and independent researcher living in Mauritius. A former Royal Marines Commando and former Wall Street investment professional, he has spent more than four decades living and working internationally across 14 countries. During that time, he worked extensively in international wealth management, cross-border asset protection, international business structuring and global residency planning.
Today, Scott's focus is no longer on managing money or providing professional advice. Instead, through MauritiusWealth.mu, he writes independent educational articles designed to help successful African business owners ask better questions, make better decisions and, when appropriate, identify the right expertise to help protect everything they have spent a lifetime building.
His articles are published solely for general educational and informational purposes and should not be regarded as legal, financial, tax, immigration, investment or other professional advice. Every business owner's circumstances are unique, and readers requiring professional assistance should always consult an appropriately qualified and licensed professional.
Expert Resources
- World Bank de-risking surveys and correspondent banking impact
World Bank fact-finding work describing why banks restrict or terminate relationships and how this affects cross-border payments and access to finance. Read the report - IMF analysis on withdrawal of correspondent banking relationships
IMF staff discussion note examining drivers and consequences of correspondent banking withdrawals, including the role of AML and compliance pressures. Read the paper - BIS and CPMI report on correspondent banking
Central bank and payments infrastructure perspective on correspondent banking decline and the compliance and risk factors driving it. Read the report - FATF trade-based money laundering risk indicators
Practical indicators used by public and private sector actors to identify suspicious trade patterns relevant to commodity and cross-border trade flows. Read the report - OECD harmful tax practices and substance focused transparency framework
OECD guidance and peer review framework explaining international expectations around transparency and substance in cross-border structures. Read the framework - African Development Bank brief on confirming banks and trade finance in Africa
AfDB analysis linking correspondent banking pressures to trade finance constraints and explaining why trade settlement reliability matters for African firms. Read the brief - Financial Services Commission Mauritius overview of Global Business licensing
Official regulator guidance on Global Business licensing and the regulated application pathway through licensed management companies. Read the guidance - FSC Mauritius Guide to Global Business
Official FSC guide describing the Global Business framework and licensing expectations in Mauritius. Read the guide - OECD tax residency information for Mauritius
OECD-provided overview of Mauritius tax residency criteria for entities, useful for understanding residency concepts used in cross-border compliance reviews. Read the document - Mauritius Revenue Authority CRS guidance notes
MRA guidance notes that reference residency concepts and compliance context relevant to internationally active entities and reporting expectations. Read the guidance notes